You come home with a few coins in your pocket. Rs 5. Maybe Rs 2. A crumpled Rs 10 note.
You put them somewhere safe. A bowl near the television. A small box in the cupboard. Or the old clay gullak that has been sitting in an Indian home for generations. You are not thinking about investments. You are simply saving what is left. Jar looked at this very ordinary habit and saw something bigger.
What if saving could happen automatically, in the same small amounts, every day?
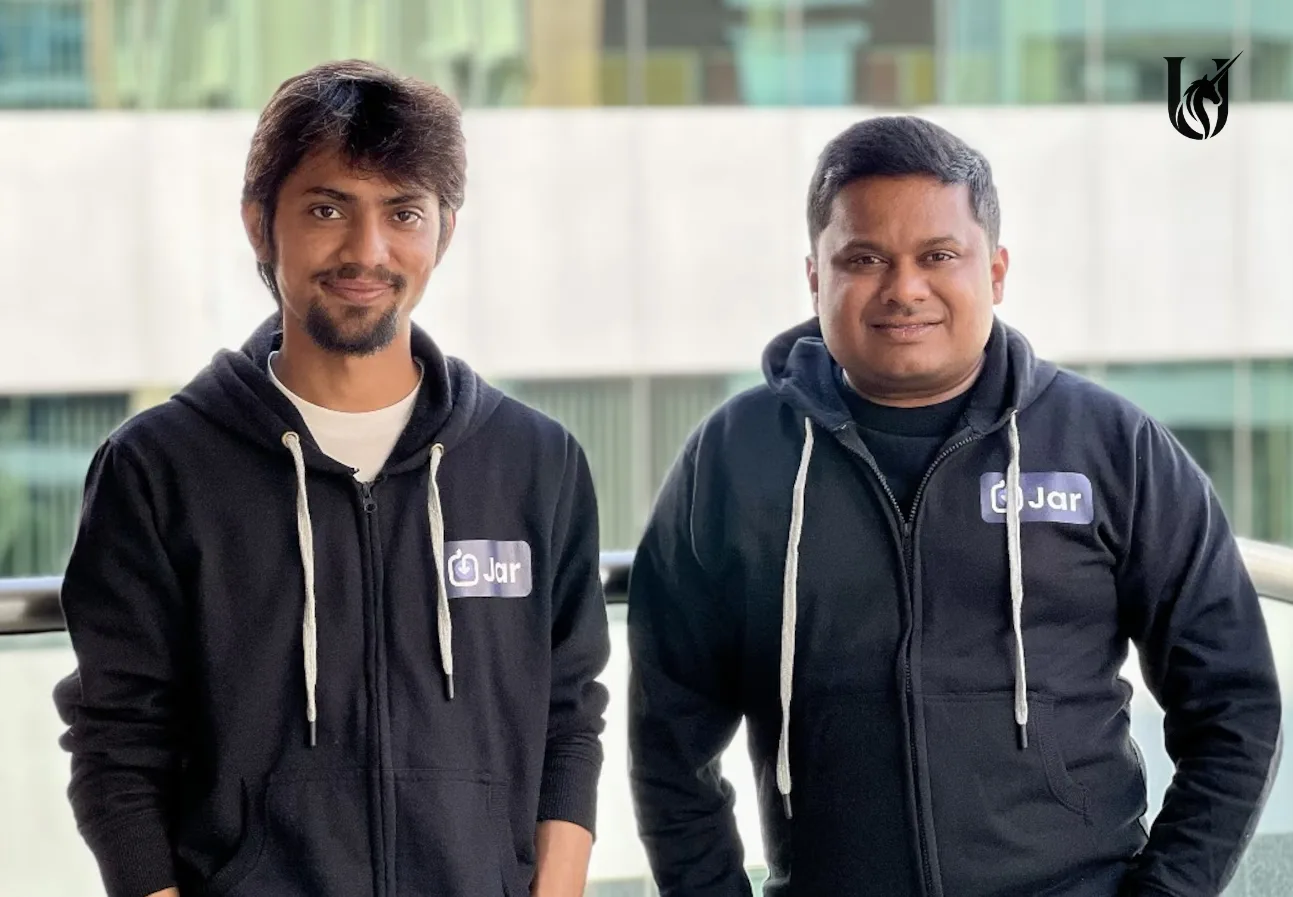
That simple question became the foundation of one of India's fastest-growing savings platforms. Founded in 2021 by Misbah Ashraf and Nishchay AG, Jar started with digital gold and a simple promise: make the first step towards saving so easy that even someone who has never invested before could begin. By FY25, the company had more than 35 Mn registered users across 12,000 pin codes.
Who Is Misbah Ashraf?
Misbah Ashraf did not arrive at Jar as a first-time founder. Before Jar, he had already built and lost businesses. His first major venture, Cibola, was a social payment startup he cofounded in 2013. Later came Marsplay, a fashion and beauty commerce platform that grew to more than a million users before the pandemic and its funding challenges eventually led to its acquisition by Foxy. These experiences became an important part of Misbah's education, not in a classroom, but in the real world of customers, money, markets, and failure.
Jar was his third major attempt.
This time, he wanted to solve a problem he understood personally.
A Small Town Beginning in Bihar
Misbah grew up around Bihar Sharif in Nalanda district in a middle-class family. His father was a teacher, and the environment around him was far removed from the startup ecosystem he would eventually enter. But Misbah developed an early urge to build something of his own. He left college and chose entrepreneurship at a time when there was no guarantee that the decision would work. That decision did not immediately lead to success. It led him to Cibola, and his first hard lesson.
Cibola: The First Failure
In 2013, Misbah and a group of friends from IIT Delhi started Cibola, a social payment venture. The idea looked promising on paper, but the business failed to find the right market. Misbah later reflected on the experience as a problem of understanding the market correctly. That failure mattered because it changed how he thought. He learned that having a product and having a market are two very different things. And when he started building again, he carried that lesson with him.
Marsplay: When Growth Was Not Enough
Four years later, Misbah returned with Marsplay. The company entered the fashion and beauty commerce space and built a strong community around creators and consumers. The platform crossed the million-user mark, giving Misbah his first real taste of what rapid consumer growth could look like.
Then COVID arrived.
Funding became difficult, consumer behaviour changed and Marsplay eventually sold its intellectual property and team to Foxy. For many founders, a second setback can be enough to walk away from entrepreneurship. Misbah did the opposite. He started looking for the next problem worth solving.
The Problem That Became Jar
The idea behind Jar was not born from a complicated financial model.
It came from a much simpler observation. Millions of Indians wanted to save but did not necessarily know how to begin. Stocks felt complicated. Mutual funds required learning. Financial planning often seemed like something meant for people who already had money. Misbah and Nishchay wanted to remove that first barrier. Their answer was to start with something Indians already understood: gold.
Why Gold?
Gold had something many financial products did not have: familiarity.
Indian families have saved in gold for generations. It has been gifted at weddings, kept for emergencies and passed from one generation to another. Jar did not ask consumers to completely change their thinking about money. It simply moved an old habit into a digital environment. Instead of asking someone to make a large investment, Jar encouraged them to begin with tiny amounts. The idea was simple: first build the habit, then build the investment. That thinking became the heart of the brand.
The Rs 10 Idea
Jar launched its gold based savings product in 2021. Its round-up model made the process feel almost invisible. If a transaction cost Rs 232, the idea was to round it up to Rs 240 and put the additional Rs 8 towards gold savings. The amount was small by design. That was the point. Jar was not trying to convince a first-time saver to suddenly become a sophisticated investor. It wanted to make saving feel as normal as spending.
Building a Digital Gullak
The founders often described Jar as a modern version of the traditional piggy bank. The old gullak had one powerful advantage: it made saving tangible. You put money inside without thinking too much about the final amount. Jar tried to recreate that behaviour digitally. The app used small, recurring actions and automation to turn saving into a routine. Over time, that routine could become a financial habit. The product was less about teaching people complicated investing strategies and more about helping them take the first step.
The First Big Break
The market responded faster than many expected. Within 18 months, Jar had crossed 11 million users and was processing around 300,000 transactions a day, according to Forbes India. By then, the company had also raised $58 million from investors including Tiger Global, Rocketship.vc and Arkam Ventures. The numbers changed the conversation around the company. Jar was no longer simply an experiment around digital gold. It was becoming a mass consumer fintech platform.
Tiger Global Bets on Jar
In February 2022, Jar raised a $32 Mn Series A led by Tiger Global, reaching a reported valuation of around $200 Mn. A few months later, another funding round of $22.6 Mn, again led by Tiger Global, took the company's reported valuation to around $300 Mn. For a company founded only in 2021, the speed was striking. But the money also brought a new responsibility. Now Jar had to prove that millions of users could become a sustainable business.
From a $300 Million Valuation to a Tough Reality
Startup valuations can rise quickly when investors believe in a company's future. But the real test comes later. Jar's 2022 valuation of more than $300 million became a widely repeated number in its success story. Yet fundraising became tougher as the startup ecosystem cooled.
In 2025, a proposed funding round involving Prosus reportedly fell apart after investors and the company disagreed over valuation. Jar wanted a valuation in the $300-350 Mn range, while potential investors reportedly valued it closer to $200-250 Mn. It was a reminder that startup success is never a straight line.
The Turnaround
Instead of chasing valuation at any cost, Jar focused on its business. The company began moving deeper into the gold value chain. It shifted from largely being a distributor to building a more vertically integrated gold platform. That changed its economics. Jar could now capture more of the value created through gold transactions rather than relying mainly on commissions. At the same time, the company began expanding beyond its original digital-gold proposition.
The Rs 2,448 Crore Revenue Number, And the Important Detail
Jar's FY25 financial numbers look extraordinary at first glance. Its consolidated revenue reached around Rs 2,448 Cr, compared with Rs 56.4 Cr in FY24. But this number needs context. Jar changed its business model and accounting treatment after becoming more vertically integrated. Earlier, it largely recorded commissions or margins. After taking a principal role in gold transactions, it began recording the gross value of gold sold as revenue.
So the Rs 2,448 Cr figure should not be read as a simple 40x increase in underlying operating income. The more comparable operating revenue was Rs 208 Cr in FY25, up ninefold, while the company reduced its loss before ESOP costs to around Rs 35.23 Cr from Rs 104 Cr.
When Jar Finally Started Making Money
This was perhaps more important than the valuation headlines. Jar said it had become profitable in the final quarter of FY25 and remained profitable for the following two quarters. TechCrunch reported that the company had achieved after-tax profitability for two consecutive quarters. That changed the story. Jar was no longer simply a heavily funded growth startup. It was beginning to show that a mass-market savings product could also move towards financial sustainability.
35 Million Users: The Real Scale Story
By FY25, Jar said it had served more than 35 Mn registered users across 12,000 pin codes.
More than 95% of these users were saving formally for the first time, while around 60% came from Tier-2 and Tier-3 cities and towns. That is important because Jar's original thesis was never about serving only India's wealthy investors. It was about reaching people who were outside the traditional investment conversation. The same person who might hesitate before opening a mutual fund account could still understand putting Rs 10 into gold.
From Gold Savings to a Bigger Financial Platform
Jar's ambition has gradually moved beyond its first product.
The company expanded into jewellery through its Nek brand and entered insurance distribution. Nek itself grew into a meaningful business, offering gold, silver, diamond and lab-grown diamond jewellery without holding traditional inventory in the same way as a conventional retailer. Jar has also expanded its payments capabilities, including UPI-based payments, creating more reasons for customers to return to the app. The strategy is becoming clearer: acquire a user through saving, build trust through gold, and then offer more financial and commerce products over time.
The Rs 4,900 Crore Valuation Story
Jar's valuation story has also changed dramatically. In 2022, the company was valued at around $300 million during its funding round. Then came the difficult 2025 fundraising environment.
By December 2025, Moneycontrol reported that Jar was in talks to raise more than $100 million at a valuation of around $550 Mn, with WestBridge Capital having issued a term sheet. The discussions were still at an early stage, so this should be described as a proposed valuation, not a completed funding valuation. At roughly Rs 89 to the dollar, $550 Mn would be around Rs 4,900 Cr.
That makes the story much more interesting than simply saying Jar became a Rs 5,258 crore company. It shows a startup that went through a valuation reset, improved its economics and then returned to the fundraising table from a stronger position.
What Happened to Misbah Ashraf?
Misbah became Jar's Chief Product Officer and played a central role in shaping the product and user experience. His journey has now stretched across three very different businesses: payments, social commerce and fintech. The first two taught him what failure feels like. Jar showed him what happens when those lessons are applied to a problem that millions of people already understand.
Forbes 30 Under 30 Recognition
In 2023, Misbah was named to Forbes India's 30 Under 30 in the Consumer Tech category. At the time, Forbes highlighted Jar's more than 11 million users, roughly 300,000 daily transactions and $58 million in funding. Misbah was also listed in Forbes 30 Under 30 Asia 2023.
The recognition was not simply about one successful startup. It reflected the unusual path behind it, a young founder who had already experienced two entrepreneurial setbacks before finding his strongest product-market fit.
Misbah Ashraf’s Net Worth
There is no reliable public source that currently establishes Misbah Ashraf's personal net worth.
This distinction matters. Jar's valuation cannot be treated as Misbah's personal wealth because the company is privately held and the founders' current ownership percentages are not fully public. So while Jar has been reported at valuations ranging from around $300 Mn historically to a proposed $550 Mn in later fundraising talks, it would be misleading to convert those numbers directly into Misbah's net worth.
The Brand Was Never Really About Gold
Gold was the entry point. The bigger idea was behaviour.
Jar understood that many people do not need another lecture about why they should save. They need a product that makes the first action easy. That is why the brand's strongest insight was not “Indians love gold.” It was that people already know how to save in small amounts; they just needed technology to make the habit easier to continue.
What Misbah’s Failures Taught Him
Cibola taught Misbah that a product cannot survive on assumptions about the market. Marsplay taught him that user growth alone cannot protect a company when the external environment changes.
Jar brought both lessons together.
Instead of building something people might eventually need, Misbah and Nishchay started with a behaviour millions of Indians already had and built technology around it. That difference helped Jar move from an interesting idea to a mass-market product.
The Bigger Lesson From Jar
The most powerful part of Misbah Ashraf's story is not the funding. It is the sequence.
Failure. Reflection. Another attempt. Another setback. Then a simpler idea.
Jar did not begin by trying to become a giant fintech company. It began with a question about spare change. Today, that question sits behind a platform with tens of millions of users, hundreds of crores in operating revenue and an expanding financial ecosystem. And that may be the real lesson from Misbah's journey:
Sometimes the biggest businesses are hiding inside the smallest habits
The Unicorn Magazine:- Editing by Ananya