Shares of Lenskart Solutions surged as much as 11.1% to an all-time high of Rs 767.40 on November 5, 2026, after the eyewear retailer reported more than doubling its consolidated net profit in Q2 FY27. The stock's rally also received support from positive brokerage commentary, with several analysts maintaining bullish ratings and raising their price targets.
The shares opened at Rs 745.05 on the BSE, against the previous closing price of Rs 691, before touching the intraday high. At around 11:31 AM, the stock was trading at Rs 733.80, up 6.2%, giving the company a market capitalisation of approximately Rs 1.27 lakh crore.
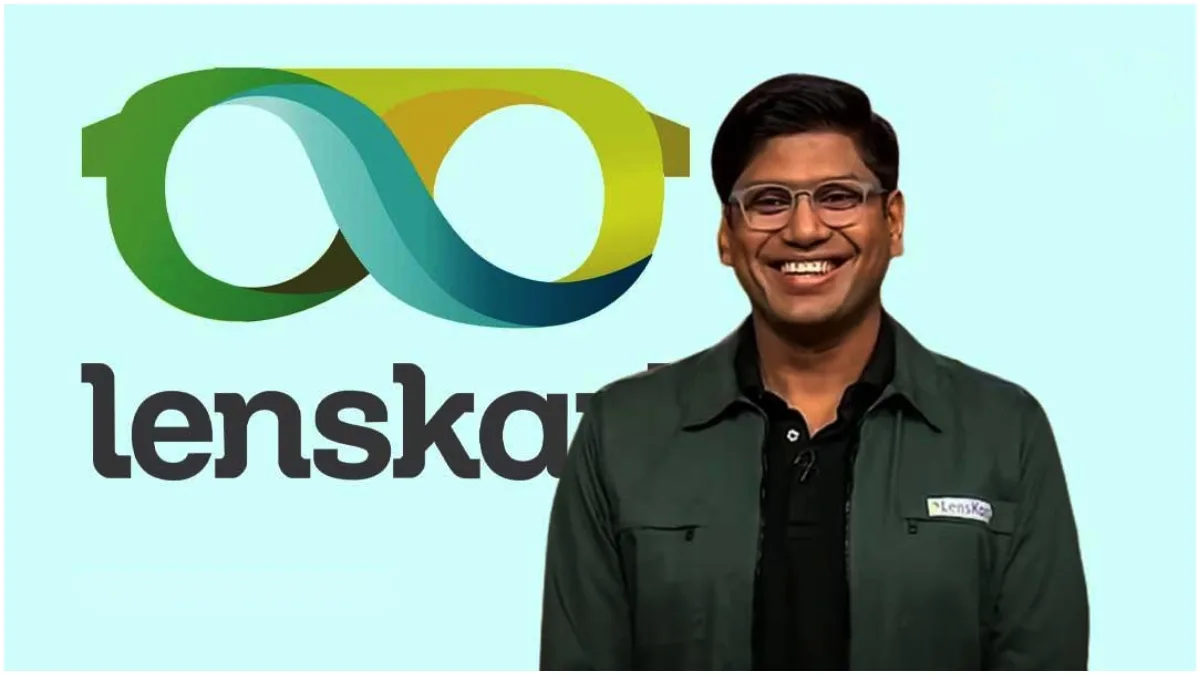
Founded by Peyush Bansal, Neha Bansal, Amit Chaudhary and Sumeet Kapahi, Lenskart has expanded from an online eyewear retailer into an omnichannel business spanning retail stores, manufacturing and international markets.
Lenskart's Q2 Profit More Than Doubles
Lenskart reported consolidated net profit of ₹227.08 crore in Q2 FY27, up 122.1% year-on-year (YoY) from ₹102.22 crore in the corresponding quarter last year.
Revenue from operations increased 35.7% to ₹2,845 crore from ₹2,096 crore in Q2 FY26.
The company's total expenses rose 31% to ₹2,596.8 crore during the quarter, indicating that revenue growth outpaced cost expansion.
According to the company's investor presentation, EBITDA before Ind AS 116 increased 65% YoY, while the corresponding margin expanded to 13.8% from 11.1% a year earlier.
Brokerages Maintain Bullish Outlook On Lenskart
The strong quarterly performance prompted several brokerages to reiterate their positive outlook on Lenskart.
Jefferies maintained its 'Buy' rating and a price target of ₹780, citing strong growth and improving margins. The brokerage highlighted the company's expansion into new customer segments through Hustlr Club, its premium retail format evolv and smart glasses.
Nomura also retained its 'Buy' recommendation with a target price of ₹888. It pointed to operating leverage across domestic and international operations, alongside manufacturing efficiencies and improved rental leverage.
HSBC upgraded Lenskart to 'Buy' and raised its target price to ₹790. The brokerage highlighted India's same-store sales growth of around 21% and international growth of 23% in constant-currency terms.
CLSA maintained its 'Outperform' rating with a target of ₹773, noting that EBITDA exceeded consensus estimates by around 3%.
Macquarie retained its 'Outperform' rating with a target price of ₹750. It highlighted stronger India EBITDA growth, improved product realisations and the potential of AI-led eye testing to increase testing capacity.
These are brokerage estimates and recommendations, not guaranteed future share prices.
Store Expansion And Manufacturing Drive Growth
Lenskart added 165 net stores during Q2 FY27, taking its total active store network to 3,624. Of these additions, 143 were in India and 22 were in international markets.
India's same-store sales growth reached 20.8%, while eyewear volumes increased 26.5% to approximately 86 lakh units.
The company also reported 40.4% growth in global eye tests to 80 lakh during the quarter.
Manufacturing remains another important part of its growth strategy. In-house frame manufacturing increased 71.7% YoY, while lens manufacturing grew 52.2%. The company's consolidated product margin stood at 70%, compared with 69.2% a year earlier.
For Lenskart, the combination of store expansion, higher sales volumes, premiumisation and manufacturing integration is becoming increasingly important to its profitability.
However, the stock's premium valuation remains an important consideration for investors, particularly as the company continues investing in expansion and faces expectations of sustained high growth.
The latest rally reflects investor confidence in Lenskart's earnings momentum, but its ability to maintain revenue growth and expand margins will remain central to its long-term market performance.
Also read: Peyush Bansal’s Lenskart Q2 FY27 Profit Jumps 125% To Rs 232.5 Cr, Revenue Rises 36%
Disclaimer: This article is for information purposes only and is not investment advice. Investments in securities are subject to market risks. Please read the official offer documents before investing.